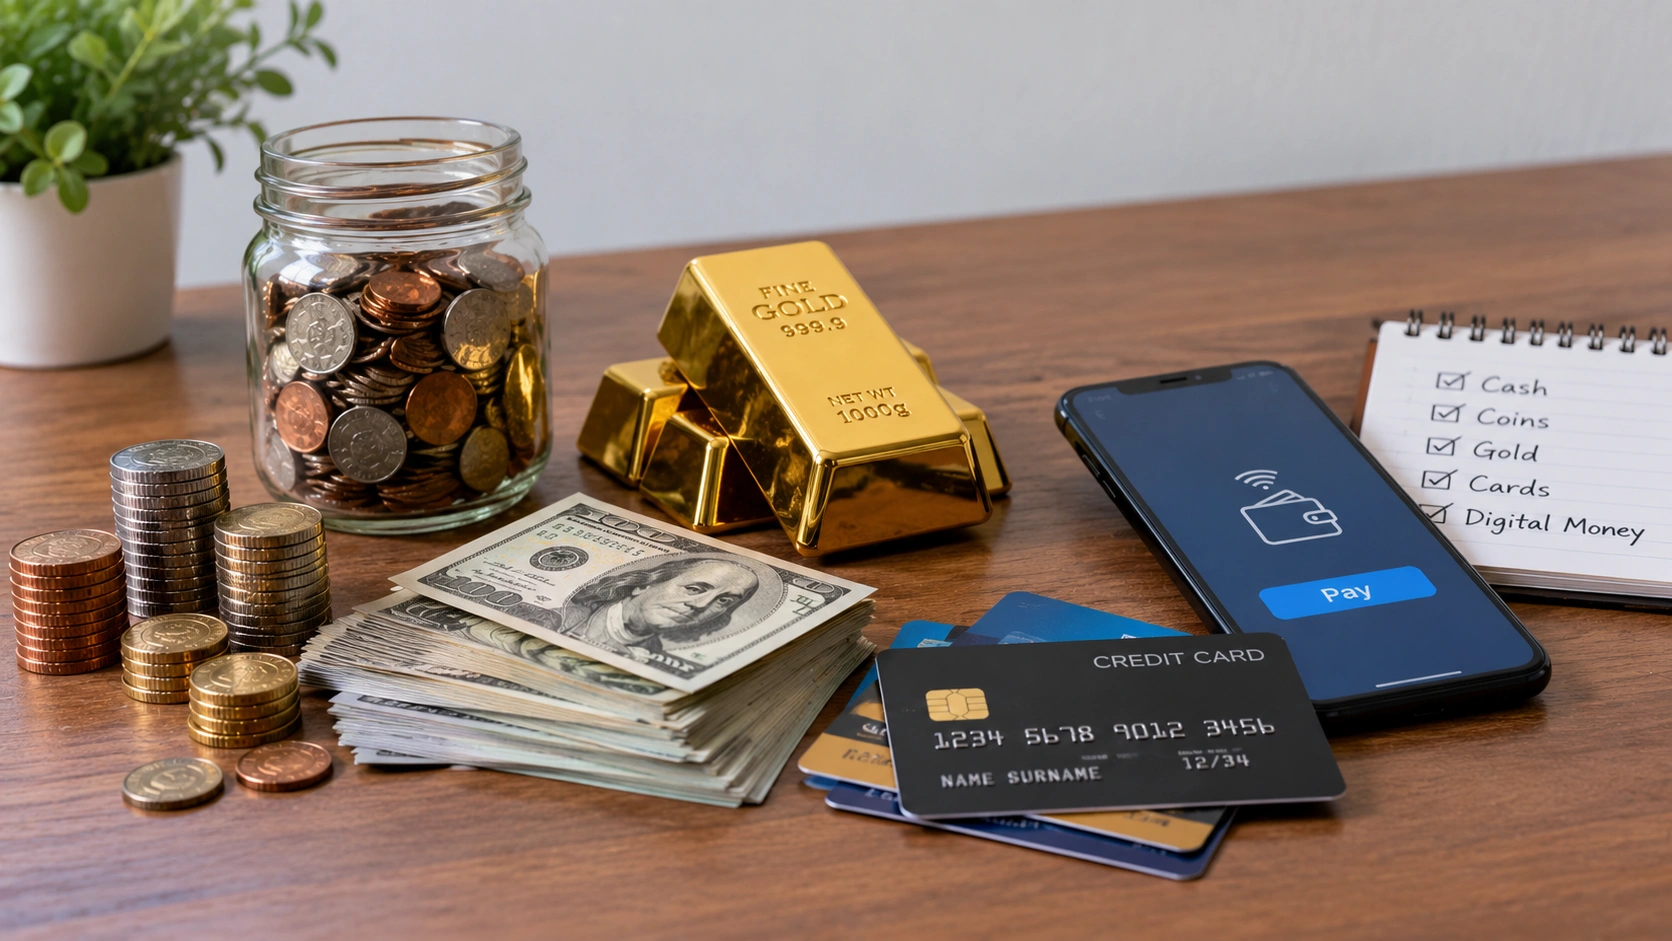
The term money type refers to the different forms money can take and the ways people use it to buy goods, pay for services, save wealth, or transfer value. Money is not limited to the notes and coins in a wallet. Modern economies use several forms, including physical cash, bank deposits, electronic payments, digital currencies, and other monetary instruments. Understanding these forms can make everyday financial decisions easier and help explain how the banking system and economy operate. Whether you are a student, consumer, business owner, or simply curious about finance, learning the differences between various forms of money provides a useful foundation for understanding how modern payments and financial systems work.
What Does Money Type Mean?
A money type is essentially a category used to describe a particular form or function of money. Economists often examine money according to how easily it can be used for transactions and how it is created or represented. Physical currency is one familiar example, while funds held in a bank account represent another. Both can be used to make payments, but they operate through different systems and have different characteristics. Understanding these distinctions helps explain why money can exist in several forms at the same time.
In everyday life, people rarely think about the form their money takes. A customer might pay with cash at a local store, use a debit card at a supermarket, or transfer funds through a banking application. Although these transactions feel different, they all involve transferring purchasing power from one party to another. The important difference is how that value is represented, stored, and transferred. Learning about each money type makes it easier to understand modern payment methods and financial services.
Physical Money: Coins and Banknotes
Physical money includes coins and banknotes issued for use as currency within an economy. It is one of the easiest forms of money to understand because people can directly hold and exchange it. Coins are generally used for smaller denominations, while banknotes represent larger values. Physical currency can be used without requiring a bank account, internet connection, or payment application, making it particularly useful in situations where electronic payment systems are unavailable.
Cash also has practical advantages for budgeting because spending is immediately visible. For example, someone carrying a fixed amount for groceries can easily see how much remains after each purchase. However, physical money also has disadvantages. It can be lost, stolen, or damaged, and carrying large amounts may be inconvenient. Despite the growth of digital payments, cash continues to play an important role in many economies because it is familiar, widely accepted, and straightforward to use.
Fiat Money and How It Works
Fiat money is currency that does not have its value based on being directly convertible into a fixed amount of a physical commodity such as gold. Its value is supported by factors including government authority, economic activity, public confidence, and the monetary system. Most modern national currencies are fiat currencies. Their purchasing power can change over time because inflation, interest rates, economic growth, and other conditions influence the economy.
A useful real-life example is the money people use for everyday purchases in countries around the world. A banknote has little value as a physical object compared with the amount printed on it. Its usefulness comes from the fact that people generally accept it as payment and trust the monetary system behind it. Central banks play an important role in managing monetary conditions, while governments establish legal frameworks for currency. This makes fiat currency a central part of modern economic life.
Bank Money and Deposit Money
Bank money refers to funds recorded in bank accounts rather than physical notes and coins. When a person receives a salary directly into a checking account, the balance shown by the bank represents money that can be used for payments. Consumers can transfer these funds through cards, bank transfers, checks, or electronic payment systems. This form of money is especially important because modern economies conduct enormous numbers of transactions without physical cash changing hands. For more: XAUUSD Price: Gold Price, Trends & Trading Guide
Deposit money also demonstrates why a bank balance is different from a pile of banknotes stored at home. The balance represents a claim recorded within the banking system, and payments involve changing account records between parties. Banks operate under financial regulations designed to support stability and protect depositors, although the exact protections differ between countries. Understanding bank deposits is particularly useful for anyone learning about personal finance because savings accounts, checking accounts, and electronic transfers are all connected to this form of money.
Digital Money and Electronic Payments
Digital money is value represented electronically rather than as physical notes or coins. Bank balances accessed through mobile applications are a common example. When someone pays a utility bill online, transfers money through a banking application, or purchases an item using a digital payment service, the transaction is generally processed electronically. Digital payments have become increasingly convenient because they allow people to move funds quickly without handling physical currency.
Electronic money can also make transactions easier to track. A consumer may review a transaction history to see when and where payments were made, while businesses can receive payments without handling large amounts of cash. However, digital payment systems depend on technology, financial institutions, telecommunications networks, and security controls. Internet outages, technical failures, fraud attempts, or account-access problems can create challenges. For this reason, responsible users should protect passwords, enable appropriate security features, and monitor account activity regularly.
Commodity Money and Its Historical Role
Commodity money is a form of money that has value connected to the commodity from which it is made or represented. Historically, societies have used items such as precious metals, livestock, salt, shells, and other goods as mediums of exchange. Gold and silver became especially important in many monetary systems because they were durable, relatively scarce, divisible, and widely valued. Commodity-based systems helped shape the development of money before modern fiat currencies became dominant.
The historical role of commodity money helps explain why precious metals remain important in financial discussions today. Gold, for example, is no longer the standard form of everyday currency in most countries, but it is still traded as a commodity and held as an investment asset. Unlike ordinary currency, gold has physical properties and an established market value independent of being issued as national money. Studying commodity money therefore provides useful historical context for understanding how modern monetary systems developed.
Cryptocurrency as a Modern Money Type
Cryptocurrency is a digital asset that generally uses cryptographic technology and distributed networks to record transactions. Bitcoin is the best-known example, although thousands of other cryptoassets exist. Unlike traditional national currencies, cryptocurrencies may operate without a central monetary authority controlling the network. Transactions can be recorded on blockchain-based systems, depending on the particular cryptocurrency and its underlying technology.
Whether cryptocurrency should be considered money depends partly on the definition being used. Traditional economists often evaluate money through functions such as serving as a medium of exchange, a unit of account, and a store of value. Some cryptocurrencies can perform certain functions, but their prices may fluctuate considerably, limiting their usefulness as stable everyday money. Regulation also differs significantly between countries. Anyone considering cryptocurrency should understand its volatility, technology, legal treatment, security risks, and potential for loss before using it.
Money Supply and Different Categories
Economists often classify money according to how liquid it is, meaning how easily it can be used to make purchases. Narrow measures generally focus on highly liquid forms such as currency and certain transaction deposits. Broader measures may include additional types of deposits and financial assets that can be converted into spending power relatively easily. These classifications help economists and policymakers analyze the amount of money circulating through an economy.
Money supply matters because changes in monetary conditions can influence economic activity, inflation, borrowing, and spending. Central banks monitor financial conditions and use monetary policy tools to influence interest rates and broader economic conditions. However, the relationship between money supply and economic outcomes is complex. Consumer behavior, bank lending, government policy, production, expectations, and global conditions can all affect what happens in the economy. Understanding money categories therefore requires looking beyond physical cash alone.
How to Choose the Right Money Type
For everyday consumers, the most suitable form of money depends on the situation. Cash can be useful for small purchases, budgeting, or locations where electronic payments are unavailable. Bank deposits are convenient for receiving income, paying bills, and managing savings. Digital payment services can make transfers and online purchases faster, while cards provide another practical way to access funds held in an account.
The best approach is usually not to depend entirely on one form. Keeping appropriate funds in a bank account while maintaining access to a reasonable amount of cash can provide flexibility. Digital payment users should also maintain good cybersecurity habits and review transactions regularly. Businesses may need several payment options because customers have different preferences. Understanding the advantages and limitations of each money type allows people to make informed choices rather than selecting a payment method simply because it is popular or convenient.
Frequently Asked Questions
What is a money type?
A money type describes a particular form or category of money, such as cash, bank deposits, digital money, fiat currency, or commodity money. Different forms can serve similar purposes while operating through different systems.
What are the main types of money?
Common categories include physical currency, fiat money, bank or deposit money, digital money, and historically, commodity money. Cryptocurrency is another modern digital asset that may perform some monetary functions.
Is cash still an important form of money?
Yes. Cash remains useful because it can be exchanged directly, does not normally require an electronic payment network, and is familiar to consumers. Its importance varies between countries and communities.
Is digital money the same as cryptocurrency?
No. Digital money can include electronic bank deposits and other electronically represented funds, while cryptocurrency generally uses decentralized or distributed technology. They have different structures, risks, and regulatory environments.
Why is understanding money types important?
Understanding different forms of money helps people make better decisions about payments, banking, saving, and financial security. It also provides a clearer picture of how modern economies and monetary systems function.
Conclusion
Understanding the different forms of money makes it easier to see how modern financial systems operate. Physical currency remains useful for direct transactions, while bank deposits and electronic payments support much of today’s commercial activity. Fiat currency provides the foundation for most national monetary systems, whereas commodity money offers historical context for how societies exchanged value before modern currencies became widespread.
There is no single money type that is perfect for every situation. Cash, bank deposits, digital payments, and newer financial technologies each have different benefits and limitations. By learning how these forms work, consumers and businesses can make more informed financial choices. For a deeper understanding, explore related topics such as how banking systems work, personal finance basics, and digital payment methods to build a stronger foundation in money and finance.